ESG communications Singapore desks fail in public when marketing language outruns what the company can disclose, prove, or defend on the same day. Boards and investors now read sustainability claims against listing and reporting rules; consumers read them against fair-trading expectations. Theatre—vague “green” adjectives, orphan targets, or a homepage that contradicts the sustainability report—creates a trust gap before any regulator asks a question.
This guide is for corporate communications, public affairs, investor relations, and sustainability-reporting operators in Singapore who must talk about ESG without inventing progress. It is educational process hygiene—not legal or investment advice, and not a substitute for counsel or assurance providers.
Educational note (YMYL): Rules change. Check live text on SGX Practice Note 7.6, ACRA’s reporting timeline, CCS quality-related claims, and MAS ESG fund disclosure guidance. Nothing here guarantees clearance or enforcement outcomes.
Neuwark Communications supports Singapore public-affairs work from Level 39, Marina Bay Financial Centre Tower 2, 10 Marina Boulevard, Singapore 018983 (+63 923 859 6587 · hello@neuwarkcommunications.com). Soft path: Singapore public affairs · Singapore government relations · Singapore crisis and issues communications · Contact. Related: Public consultation responses · Issues management before the crisis call · GR vs public affairs buyer split.
Direct answer: what “without greenwash theatre” means
| Theatre habit | Disclosure-hygiene habit |
|---|---|
| Homepage says “carbon neutral / eco / sustainable” without scope or evidence | Claims match the latest sustainability report or filings, with scope and period stated |
| CEO video announces a 2030 target missing from governance papers | Targets appear where the board already owns them; spokespeople quote the published line |
| Marketing invents a new ESG label for a product pack | Product claims follow CCS-style truth, clarity, evidence, and material-information principles |
| IR deck and consumer ads use different numbers for the same metric | One source-of-truth table; every public line cites the owner and as-of date |
| “Fully ISSB aligned” said loosely in media | Compliance language tracks what SGX / ACRA require for your tier and year |
Who this is for / who should skip
| Use this operating rhythm | Hand off |
|---|---|
| PA / Corp Comms / IR aligning external ESG narrative to filings | Legal opinions on Listing Rule 711A/711B—counsel only |
| Regional hubs briefing Singapore spokespeople before an ESG media day | Assurance opinions—registered providers only |
| Sustainability + Comms co-owning a claim register | Retail ESG fund disclosures—MAS Circular CFC 02/2022 + counsel |
What Singapore’s disclosure backdrop forces onto communications
You do not need to recite every rule to run a clean desk. You do need to know why theatre is expensive: public ESG language now sits next to mandatory sustainability reporting for listed issuers, phased climate-related disclosures, and consumer-facing claim standards that treat vague “green” language as a fairness problem.
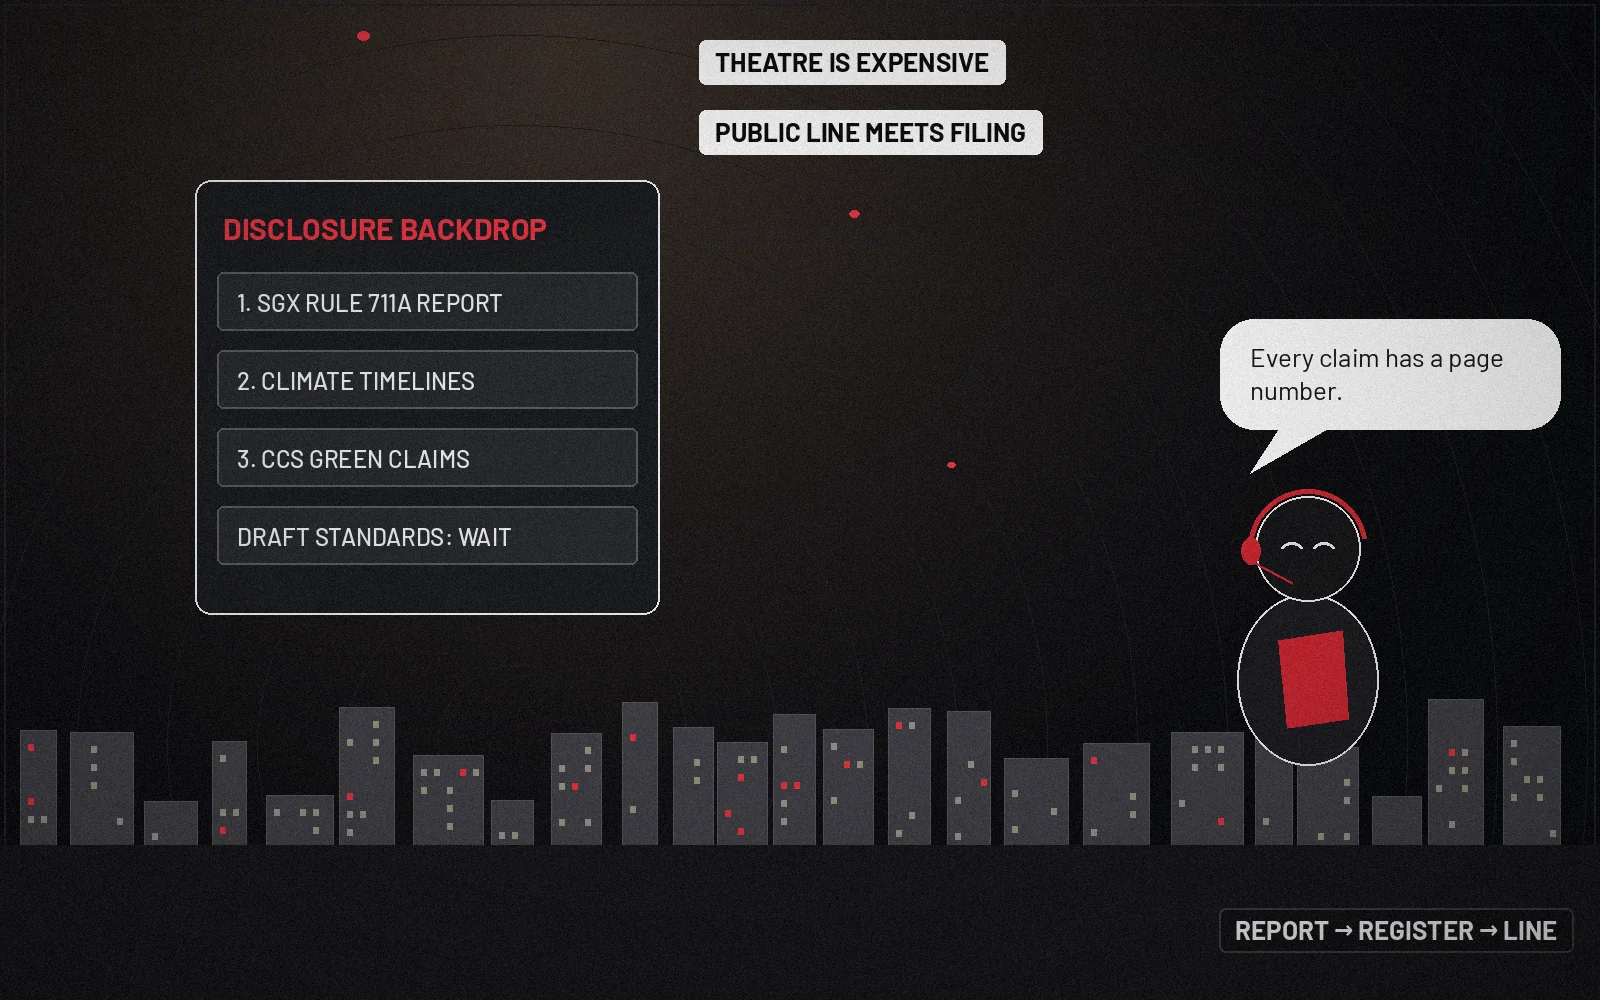
Listed-issuer reporting. SGX Listing Rule 711A requires an annual sustainability report against Rule 711B primary components. Practice Note 7.6 frames board responsibility, material ESG factors, climate-related disclosures, policies/performance/targets, framework choice, and a board statement—with IFRS S2 / ISSB-based climate content phased by issuer tier (including Scope 3 for STI constituents).
Phased climate timelines (verify live). ACRA’s requirements timeline (page last updated 27 July 2026 when checked for this article) summarises the climate-first roadmap: all SGX-listed companies report Scope 1 and 2 GHG emissions from FY commencing on or after 1 January 2025; STI constituents lead on other ISSB-based climate-related disclosures from FY2025 and Scope 3 from FY2026; further ISSB-based CRD phases by market-capitalisation tier into FY2028 / FY2030. ACRA and SGX RegCo extended several timelines on 25 August 2025 while keeping Scope 1–2 mandatory from FY2025 for listed companies. Large non-listed companies have later start dates on the same ACRA page—do not copy listed-company talking points onto an NLCo without checking the tier.
Consumer / product green claims. On 6 October 2025, CCS published guidance on quality-related claims (including environmental claims): claims should be true and accurate, clear, meaningful, accompanied by material information, and supportable by evidence—see the CCS announcement and go.gov.sg/guide-on-quality-related-claims. Earlier CCCS-funded work flagged vague terms such as “eco-friendly,” “green,” and “sustainable” when used without specific, verifiable detail.
Retail ESG funds (if that is your lane). MAS Circular CFC 02/2022 and the Good Disclosure Practices for Retail ESG Funds paper (MAS page dated 10 June 2026) set disclosure expectations to mitigate greenwashing risk. Corporate brand ESG is a different perimeter—the comms lesson is the same: name, methodology, and evidence must match the product.
Standards still in draft. ACRA has consulted on draft Singapore Sustainability Disclosure Standards based on IFRS S1/S2 (consultation page). Do not claim you “already comply with SFRS S2” unless counsel confirms a live obligation. None of the above invents fines or case outcomes—it sets the hygiene bar before a website line, IR day, or product pack ships.
Original element 1 — Greenwash-risk claim ladder
Map every public ESG sentence to a rung before it leaves the building. If it cannot map, it does not ship.
| Rung | Allowed if… | Needs evidence pack | Never say (unless counsel + evidence + board ownership) |
|---|---|---|---|
| Factual disclosure | Restates a number/date already in the latest sustainability report, annual report, or SGXNet filing, with period and scope | Source page + owner + as-of date | “Best-in-class ESG” with no metric |
| Progress vs prior year | Same methodology year-on-year; restatements explained | Methodology note; restatement log | “Dramatically greener” without figures |
| Target language | Target is board-approved and published; baseline year stated | Board/report excerpt; pathway owner | “On track for net zero” without published pathway |
| Product / service claim | Specific attribute (e.g. recycled content %) with conditions | Lab/cert pack; comparison basis | Bare “eco-friendly / green / sustainable” on pack or ads |
| Framework alignment | States which framework components you apply and for which period | Framework mapping table | “Fully ISSB / TCFD compliant” as a slogan |
| Assurance language | Quotes the assurer’s actual scope and level | Assurance statement excerpt | “Assured ESG report” implying the whole narrative is assured |
| Fund / product ESG label | Only inside MAS’s retail ESG fund perimeter with Circular CFC 02/2022 conditions met | Prospectus + website disclosures counsel-cleared | Renaming a non-ESG product with ESG words for lift |
Who signs off which rung
- 1. Sustainability / finance reporting — numbers, scopes, baselines, restatements.
- 2. Legal / company secretary — Listing Rule and consumer-claim risk; “compliance” wording.
- 3. IR — investor decks and Q&A must match filings.
- 4. Corp Comms / PA — plain-English translation; no adjective inflation.
- 5. Marketing / brand — product claims and campaign visuals.
- 6. Board / designated committee — material ESG factors and targets (as PN 7.6 frames board responsibility).
If two owners disagree, the more restrictive public line wins until counsel or the board upgrades it.
Original element 2 — 48-hour ESG narrative desk checklist
Singapore clock. Use before a report drop, IR day, product green claim, or reactive media hit.
T-48 to T-24
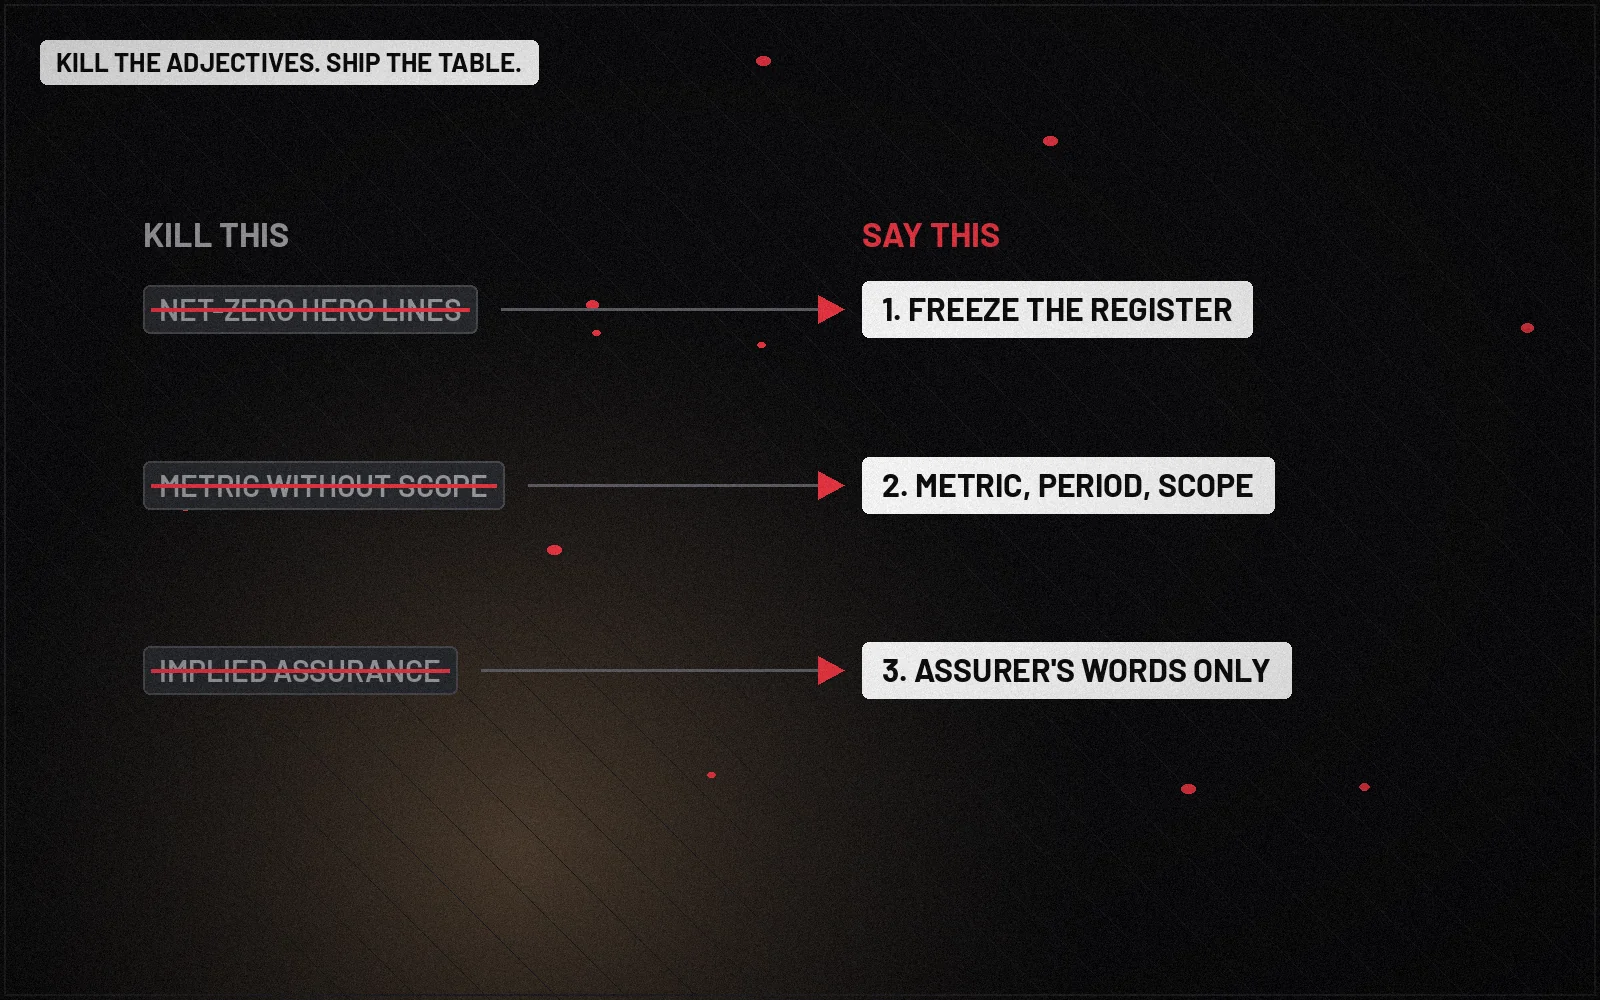
- 1. Freeze the latest published sustainability report / climate disclosures and the claim register (version ID).
- 2. Build a one-page source-of-truth table: metric → value → period → scope → page/URL → owner.
- 3. Flag every draft homepage, social, and press line not on that table.
- 4. Confirm no line implies assurance beyond the assurer’s stated scope.
- 5. Stress-test product claims against CCS’s five principles (true, clear, meaningful, material info, evidence)—CCS 6 Oct 2025.
- 6. Re-read your tier on ACRA’s timeline so spokespeople do not over-claim Scope 3 or “full ISSB.”
- 7. Cap the day to five shared numbers across IR and media Q&A.
T-24 to T-4
- 8. Legal/comms red-team: delete orphan adjectives (“revolutionary sustainable transformation”).
- 9. Prepare a holding line if a data error surfaces after publish (who speaks; where the correction posts).
- 10. Brief spokespeople: quote the published sentence; do not “improve” numbers live.
- 11. Check website ESG pages and the PDF report do not contradict on Scope 1–2.
- 12. One contact inbox for investor / media questions—not three competing replies.
T-4 to T+24
- 13. Publish only counsel-cleared packs.
- 14. Hunt stale microsites still ranking with old claims—update or noindex.
- 15. Log journalist paraphrases that upgrade your claim; correct on-record if needed.
- 16. File a short issues note at +24h: what landed, what drifted, what to fix in the register.
When an ESG story turns into an issues story, pair this with issues management before the crisis call. For disclosure-standards consultations, use public consultation response structure.
Original element 3 — Worked illustration (fictional; labelled)
Scenario (illustrative only): A fictional mid-cap SGX Mainboard issuer—not an STI constituent—runs a consumer campaign and an IR room in the same week its sustainability report goes live. No real company, fine, or market outcome is claimed.
What the report actually says (fictional): Scope 1 and 2 for FY2025 with boundary stated; a 2030 intensity target with 2022 baseline (no absolute “net zero” slogan); limited assurance only on Scope 1–2 data; one SKU uses 30% certified recycled polymer, footnoted.
Marketing’s first draft (reject): “We’re a fully sustainable, carbon-neutral brand leading Singapore’s green future—ISSB compliant and eco-friendly across our range.”
Claim-ladder rewrite (ship): “In our FY2025 sustainability report we disclose Scope 1 and 2 GHG emissions for [boundary]. We have published a 2030 emissions-intensity target against a 2022 baseline. Our [SKU] uses 30% certified recycled polymer; other products are not covered by that claim. Climate-related disclosures follow the phased requirements for our issuer tier under SGX Practice Note 7.6 / the ACRA roadmap—ask IR for the report link.”
Board questions to pre-answer: Which public sentence is not backed by the report? Who signs product “green” language? If a journalist says “carbon neutral,” what is the exact correction? Does any slide imply whole-report assurance?
Common traps
| Trap | Why it fails | Fix |
|---|---|---|
| Homepage ahead of the report | Screenshot inconsistency | Ship report language first; marketing follows the register |
| Mixing fund rules into brand copy | MAS Circular CFC 02/2022 is a fund perimeter | Separate lanes |
| Copying STI Scope 3 talking points onto a smaller issuer | Timelines differ by tier | Brief your obligations only |
| “Assured” as a halo word | Assurance scope is usually limited | Quote the assurer’s scope sentence |
| Silent on limitations | CCS expects material information with the claim | Put conditions next to the claim |
FAQ
Is ESG communications Singapore only for listed companies?
No. Listed issuers face explicit SGX / ACRA sustainability and climate-reporting rules. Unlisted companies still face CCS consumer-claim standards and counterparties who treat vague green language as a trust risk. Large NLCo start dates sit on ACRA’s timeline—verify before you speak as if you were listed.
Can we say “sustainable” in ads if we have a sustainability report?
Only with specificity and evidence. A corporate report does not automatically substantiate a product adjective. Follow CCS principles—see the 6 October 2025 announcement.
What to do next
Freeze a claim register that maps every public ESG sentence to a filing page, owner, and as-of date. Run the 48-hour checklist before the next report drop or product green claim. For a Singapore public-affairs desk to stress-test narrative versus disclosure—without theatre—start at Singapore public affairs or contact Neuwark.